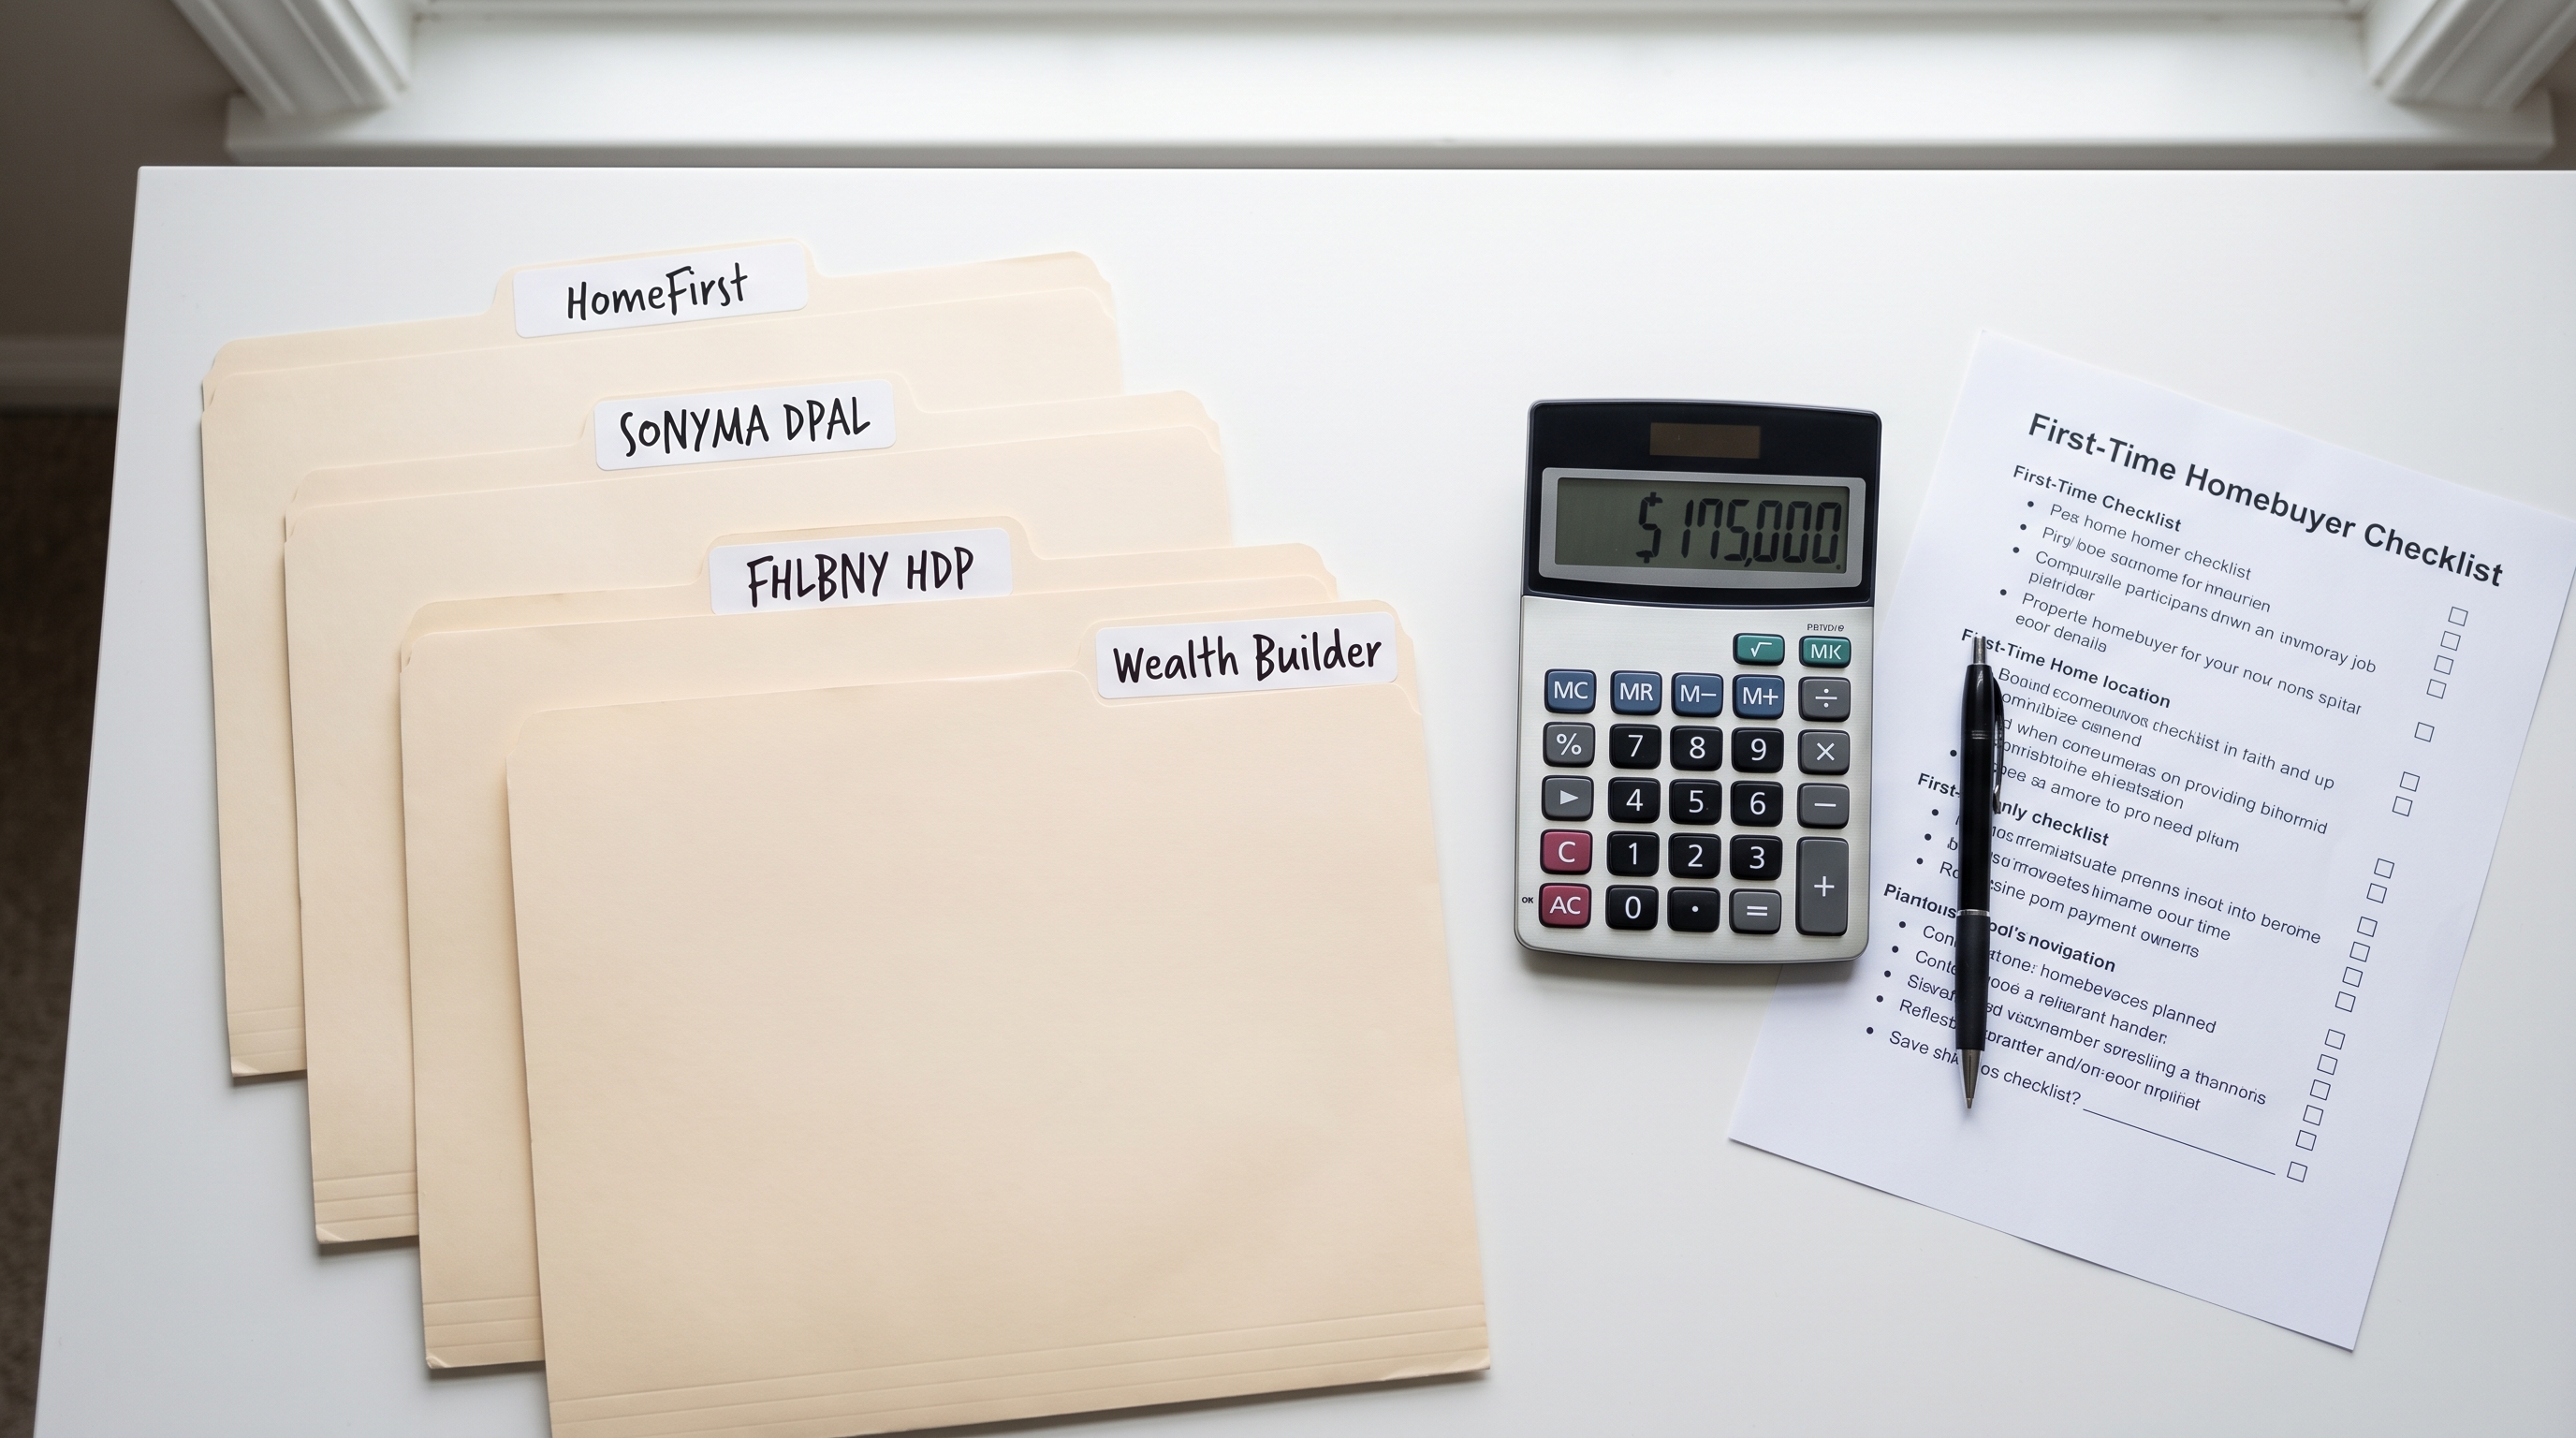
The four stackable programs are HomeFirst (up to $100,000 forgivable),1 SONYMA DPAL or DPAL Plus ($15,000 to $30,000),3 FHLBNY HDP and HDP Plus (up to $30,000 grant),2 and HDP Wealth Builder (an extra $30,000).2 Maximum stack: $175,000. Realistic stack for most buyers: $145,000, because Wealth Builder requires first-generation buyer status or a majority-minority census tract.8
We are not listing programs here. We are showing you the exact order to apply, the lenders that actually work, and the 90 to 120 day timeline that gets you to the closing table.
Here is the part most buyers miss. Failure does not come from disqualification. It comes from applying to programs in the wrong order, or using a lender that is not on all three approval lists. Get the sequence right and the stack works.7
Check Your Income Against the Eligibility Tables
Before you call a single lender, know which programs your income unlocks. Income is the only gatekeeper that disqualifies buyers immediately, and there are three different ceilings to check. Pull your last two pay stubs and your most recent tax return before reading further.
HomeFirst (120% AMI 2026)1
| Household Size | Income Cap |
|---|---|
| 1 person | $136,080 |
| 2 person | $155,520 |
| 3 person | $174,960 |
| 4 person | $194,400 |
| 5 person | $210,000 |
| 8 person | $256,680 |
SONYMA Income Lanes
- Achieving the Dream (lowest rate, DPAL Plus eligible): cap around $109,000 for 1-2 person NYC households.
- Low Interest Rate: cap $174,720 for 1-2 person NYC households. Bridge for buyers earning $109K–$174K.
- DPAL Plus requires 60% AMI and uses limited funding that suspends when exhausted.
The Decision Rule
Which programs can you stack?
- Under 60% AMI DPAL Plus + HomeFirst + HDP → $145K
- 60–80% AMI DPAL + HomeFirst + HDP → $145K
- 80–120% AMI SONYMA Low Rate + HomeFirst + HDP Plus → $145K
- Above 120% Out of HomeFirst — look at private lenders
Complete the Free Homebuyer Education Class
Every program in the stack requires a HUD-certified homebuyer education certificate before you can submit. Most buyers find this out 3 to 4 weeks too late and lose their place in the application queue. Book this week.
Two Approved Options
- ESD Free Zoom (recommended): 3 sessions, 6 hours total, biweekly schedule, $0 cost. HUD certificate issues the same week you finish.
- NHSNYC Online: $100 fee, 8 to 10 hours self-paced, same HUD certification, available 24/7.
Find the Multi-Program Lender
This is the bottleneck nobody talks about. Each program (HomeFirst, SONYMA, HDP) maintains its own approved lender list. To stack all three, you need ONE lender that appears on ALL THREE lists. Most NYC mortgage brokers are on zero or one. Pick the wrong lender and you lose $50K+ in assistance.
Confirmed NYC Multi-Program Lenders — Call This Week7
Cross Country Mortgage
646-586-3182
Strong on HomeFirst + SONYMA + HDP combinations
Emigrant Mortgage
212-850-4848
Long history with HPD programs, deep co-op experience
M&T Bank
631-774-6491
FHLBNY member that runs HDP reservations smoothly
What to Ask on the First Call
- "Are you currently active on HPD's HomeFirst lender list?"
- "Can you submit a SONYMA DPAL or DPAL Plus alongside HomeFirst on the same file?"
- "Are you an FHLBNY member able to reserve HDP funds for me?"
- "Have you closed a stacked HomeFirst + SONYMA + HDP loan in the last 12 months?"
- "How many days from application to clear-to-close on a stacked file?"
If they answer "no" or "we'll check" to any of the first three, hang up and call the next one.
Apply for HomeFirst Through an HPD Counseling Agency
HomeFirst is the anchor of your stack. Up to $100,000 forgivable, the biggest single piece. It is also the slowest. Open this file first so it processes in parallel while you handle the others.
Documents to Have Ready
- HUD homebuyer education certificate
- Last 2 years of W-2s and tax returns
- Last 2 months of bank statements (all accounts)
- 30 days of pay stubs
- Photo ID and Social Security card
- Lender pre-qualification letter (from Step 5)
Active NYC HPD counseling agencies include NHSNYC, GROWTH, Asian Americans for Equality, Bridge Street Development, and Neighbors Helping Neighbors. Email one this week.
Up to $175,000 in assistance is available — but most buyers miss it because they never ask the right lender.
Our team has helped NYC buyers stack multiple programs. Reach out and we'll walk you through exactly what you qualify for.
Mon – Sat · 9 AM – 7 PM ET
Get SONYMA Pre-Approval and DPAL
SONYMA is your mortgage and your second piece of assistance in one application. The pre-approval letter unlocks the home search, and DPAL piggybacks automatically.3
Picking Your SONYMA Track
Achieving the Dream
5.600%
vs 6.29% market average — saves $182/month on a $400K loan
Cap: $109K (1-2 person NYC)
Low Interest Rate
Below market
For buyers earning $109K to $174,720
Cap: $174,720 (1-2 person NYC)
Homes for Veterans
-0.375%
Rate discount, no origination fees, no first-time buyer requirement
Veterans default here
Reserve Your FHLBNY HDP Grant Through Your Lender
HDP is the cleanest piece of the stack. A true grant, not a loan. After 5 years in the home, you owe nothing. The 2026 funding pool closes November 27, 2026, and reservations are first-come, first-served.2
2026 HDP Funding Deadline: November 27, 2026
$31.67 million in the standard HDP pool. Once exhausted, applications stop until the 2027 round. If you're reading this in mid-2026, reserve now.
Check if You Qualify for HDP Wealth Builder
HDP Wealth Builder is the upgrade hidden in plain sight. It stacks on top of standard HDP for an additional $30,000, bringing your federal piece to $60,000.
Two Ways to Qualify
- Path 1 — First-Generation Homebuyer: Neither parent has owned a home in the last 3 years. If you are the first in your family to buy, you qualify automatically.
- Path 2 — Majority-Minority Census Tract: If the home sits in a census tract where the majority of residents are people of color, you qualify regardless of family history. Most of the Bronx, large parts of Brooklyn, Queens, and Upper Manhattan qualify.
Search for a Home Under the Price Caps
Your stack only works on properties that fit each program's rules. Searching outside these limits is the most common reason approved buyers walk away from accepted offers.
Property Types That Work
- 1-4 family homes (you must occupy one unit).
- Condos.
- Co-ops. HomeFirst is rare in including these — a major NYC advantage.
Property Types That Don't Work
- Investment properties (no owner-occupancy).
- Mixed-use buildings over a certain commercial threshold.
- Properties needing major repairs that fail SONYMA appraisal.
Tell your real estate agent on day one: "I am using HomeFirst, SONYMA DPAL, and FHLBNY HDP. I need a lender-approved property." Agents who don't know these programs will waste your time.
Close With All Programs at One Table
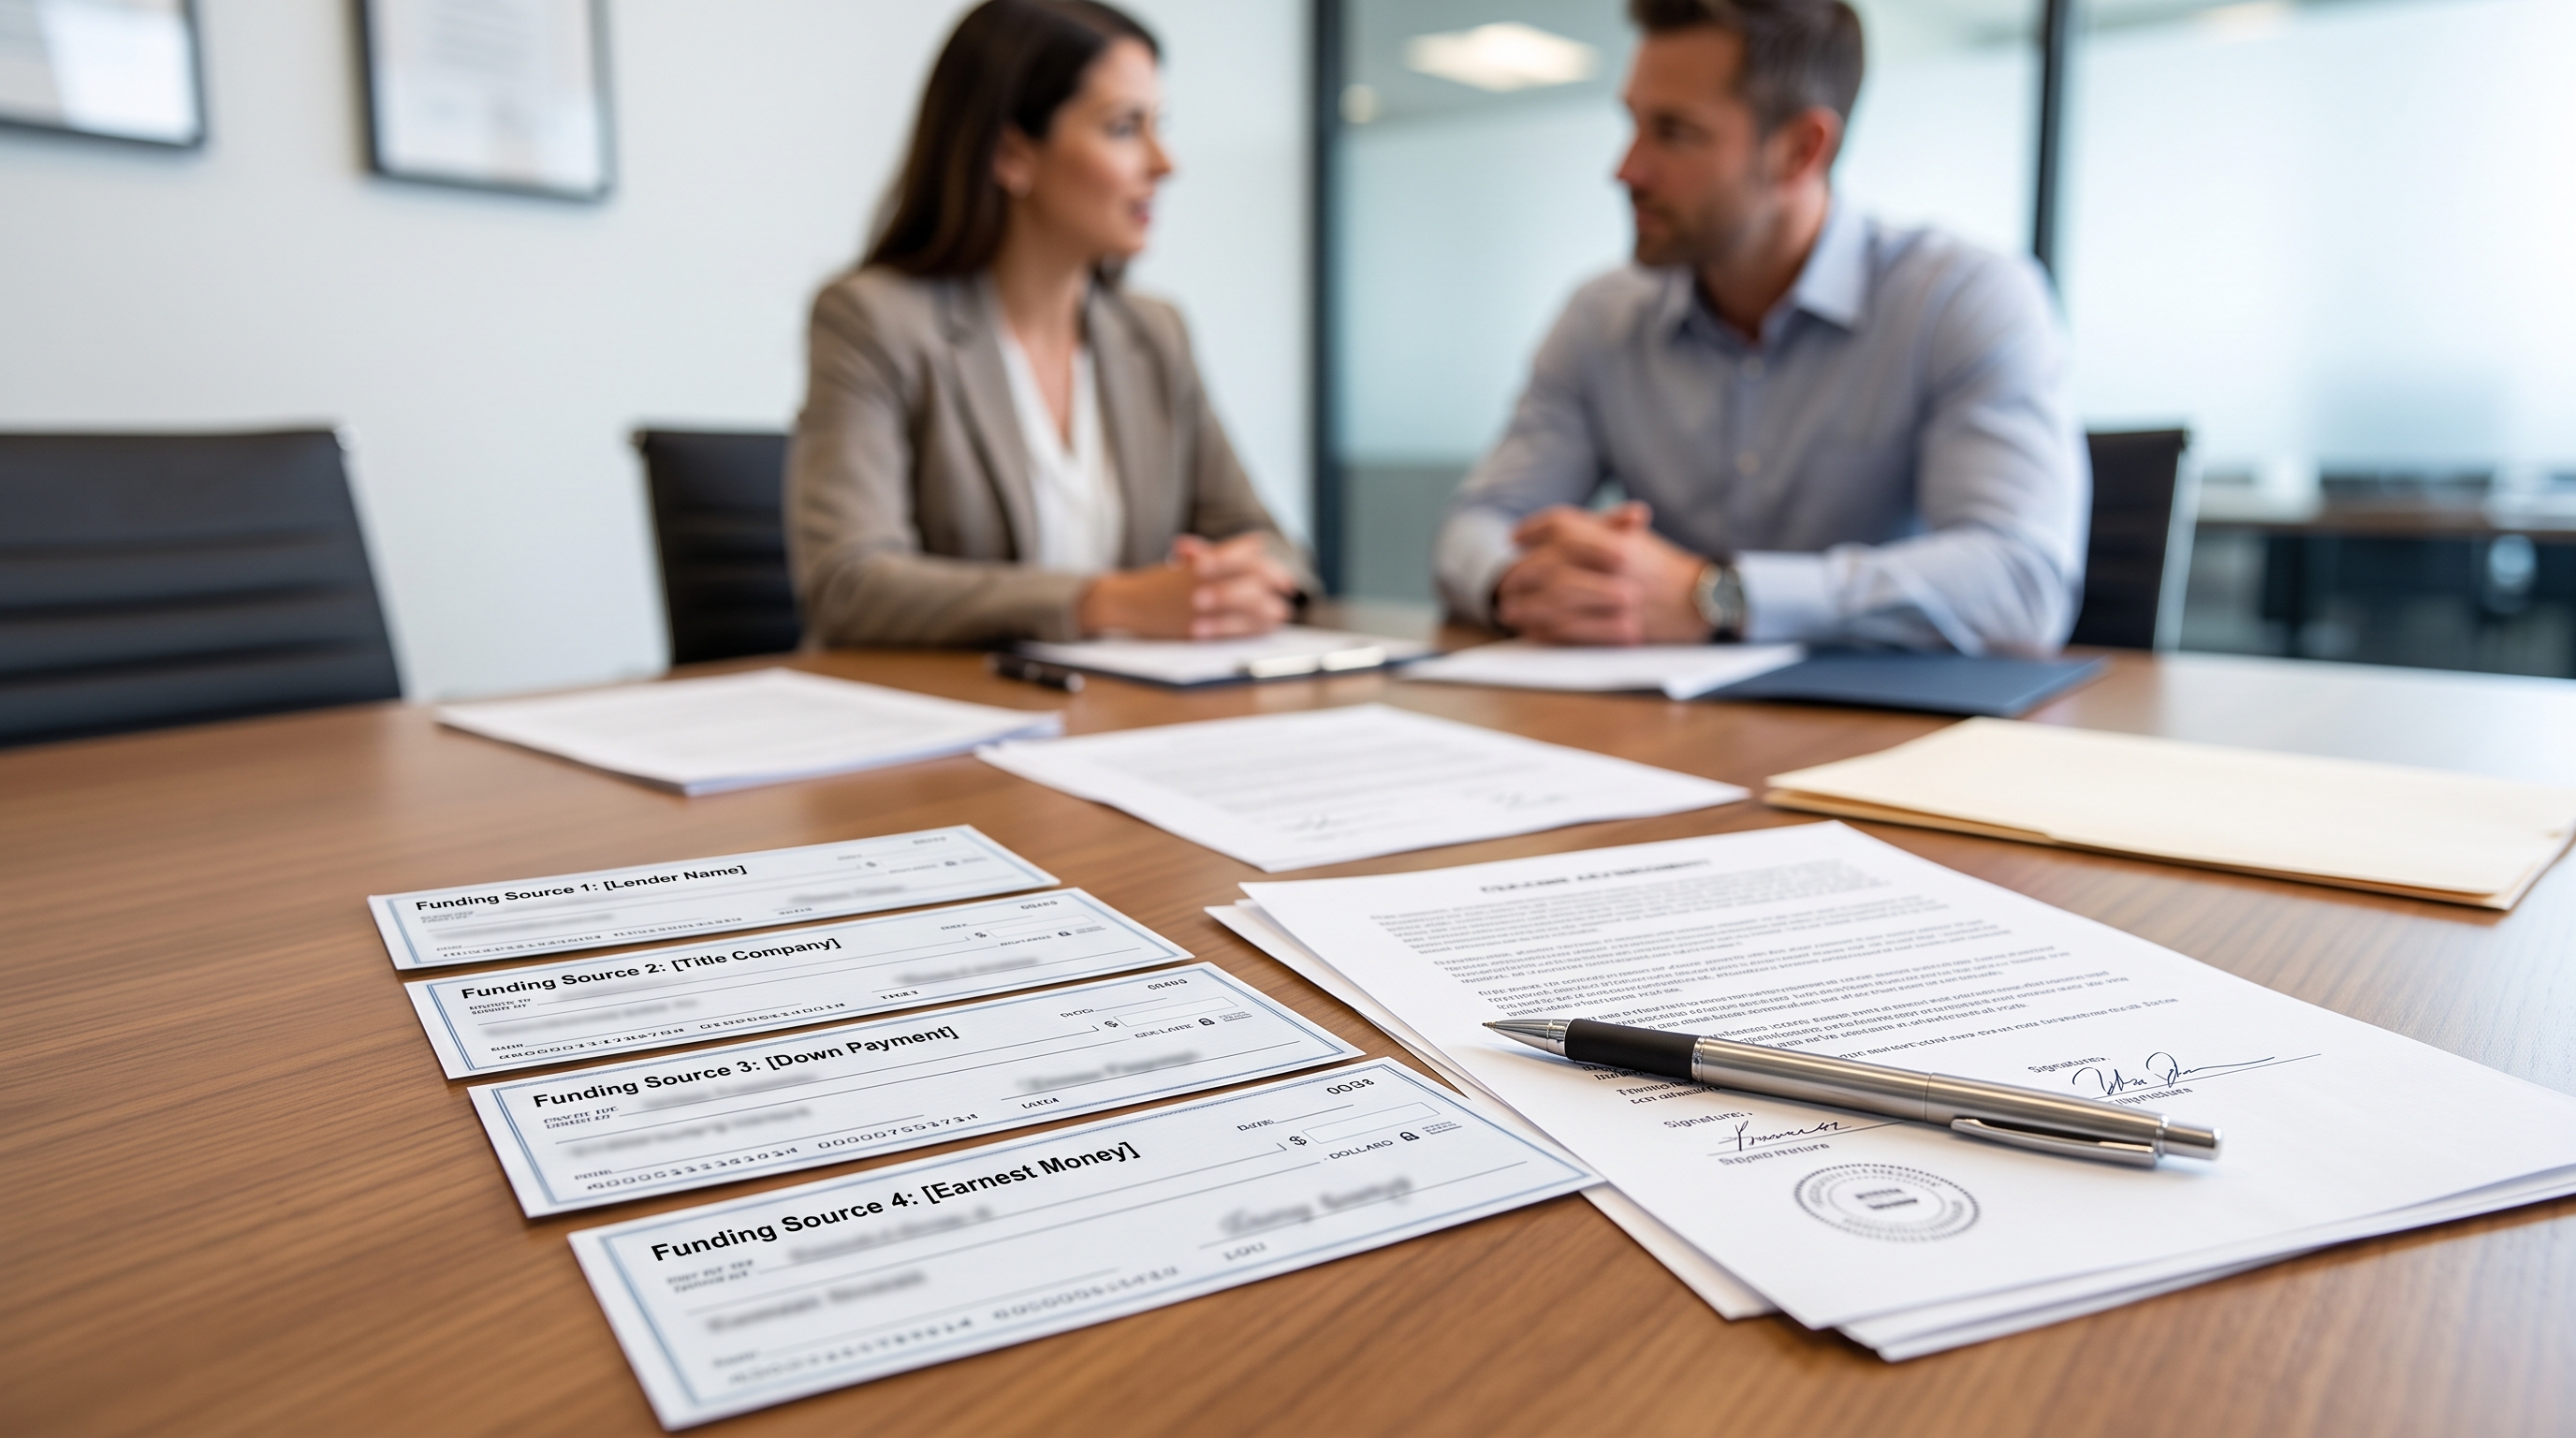
On closing day, four checks fund your purchase: your 1% cash, your SONYMA mortgage, your HomeFirst forgivable loan, and your HDP grant. The lender coordinates all of it. You sign and get keys.
Reported Example
A First-Time Buyer Family in Great Kills, Staten Island5
Total Timeline Recap
Frequently Asked Questions
Do I actually qualify if I earn $130K in NYC?
Yes. At $130K as a 1-2 person household, you're above the SONYMA Achieving the Dream cap (~$109K) but well within HomeFirst (120% AMI) and SONYMA Low Interest Rate ($174,720). Your stack: HomeFirst + SONYMA Low Interest Rate + HDP Plus. Realistic total: $130,000+ in assistance.
How long does the entire stacking process take?
90 to 120 days from your first lender call to closing. HomeFirst processing is the bottleneck. Co-op purchases add 4 to 6 weeks for board approval.
What if I earn too much for HomeFirst?
Above 120% AMI ($194,400 for a 4-person household), HomeFirst is closed. You can still use SONYMA Low Interest Rate plus FHLBNY HDP Plus — that's still $30K+ in assistance. Not the full stack, but meaningful.
Can I really get $175,000 in down payment help?
Yes, but only if you qualify for HDP Wealth Builder (first-generation buyer or majority-minority census tract) AND stack all four programs. Most buyers land at $145,000 because Wealth Builder qualification is narrower. Both outcomes are life-changing in NYC.
What if my lender isn't on all three program lists?
Switch lenders immediately. Your homebuyer education certificate, SONYMA application, and HomeFirst file all transfer. You'll lose 1 to 2 weeks but save tens of thousands. Call Cross Country Mortgage, Emigrant Mortgage, or M&T Bank.
Do I have to live in the home, and for how long?
Yes. HDP: 5 years. HomeFirst: 10–15 years. DPAL: 10 years. Selling early triggers prorated repayment, not full repayment. Renting before forgiveness is a default event.
Sources & References 8 sources
- 1 NYC Housing Preservation & Development "HomeFirst Down Payment Assistance Program"
- 2 Federal Home Loan Bank of New York "Homebuyer Dream Program (HDP) Suite"
- 3 NYS Homes and Community Renewal "Down Payment Assistance Loan (DPAL)"
- 4 NYS Homes and Community Renewal "Achieving the Dream Program"
- 5 Robert DeFalco Realty "First-Time Home Buyer Programs in New York & New Jersey"
- 6
- 7 Down Payment Scout "Down Payment Assistance New York City 2026"
- 8